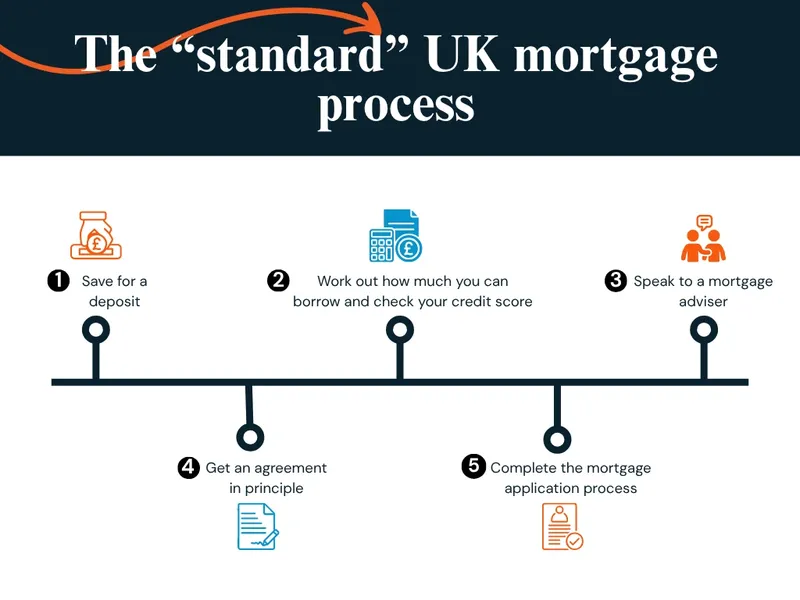
Other factors that influence the mortgage process
The mortgage process can differ slightly depending on the type of property you want to buy, such as buy-to-lets or shared ownership.
How to get a buy-to-let mortgage
When getting a buy-to-let mortgage, similar to a traditional mortgage, you need to prove you can afford the repayments, and the amount you can borrow is proportional to the projected rental earnings from the property. Buy-to-let schemes are considered higher risk by lenders, so you’ll usually need a good or excellent credit score and proof of income aside from rental earnings.
To get a buy-to-let mortgage in the UK, you typically need a 25% deposit (as opposed to the typical 5 - 20%).
Important to note is that buy-to-let is an investment scheme, rather than a direct path to home ownership. Eligibility is often stricter, including minimum and maximum age requirements, and higher personal income.
You must also decide if you want to apply as an individual or as a Limited Company (this will offer tax benefits, but requires a more specialised mortgage).
The amount you can borrow for a buy-to-let mortgage is based on the estimated average monthly rental income the property will pull in – this should cover around 125% of your mortgage interest repayments. This means a monthly rental income of £500 will be sufficient for £400 interest payment, for example.
Often, buy-to-let mortgages are interest only, which is when you only pay off the interest and not the original loan. While this improves cash flow, it means that at the end of your mortgage you still won’t own the property, and will need a plan to repay the original loan (the capital).
If you want to know more about buy-to-let properties and mortgages, read our dedicated guide about buy-to-let properties.
How to get a shared ownership mortgage
Getting a shared ownership mortgage involves buying a share of a property (usually between 25 - 75%), and paying rent on the rest to the landlord. Getting a shared ownership mortgage is slightly different to a traditional mortgage.
This type of mortgage usually requires a deposit of around 5-10% of the value of the share you are buying.
You must have an income of under £80,000 (or £90,000 in London), and either be a first-time buyer or unable to afford property currently.
You must apply for a shared ownership mortgage through a broker, such as a housing association. You cannot apply directly through a typical lender. Ensure you meet the criteria for the specific scheme you are applying through, as they’ll check your eligibility and assess if you can afford the repayments, similar to a traditional mortgage
If you pass these checks, you will then receive a mortgage offer.
If you want to know more about shared ownership, read our dedicated guide about shared ownership properties.
How to get a mortgage for an auction property
Absolutely! Using a mortgage for an auction property can be a viable option, although it requires quick action and careful planning, especially if you're buying a house at a traditional auction, as you only have a 28 days to secure financing and complete your purchase. If you're buying through the modern method, you have 56 days, which is usually enough time to secure a mortgage.
If you plan to use a mortgage to buy your auction property, you should have a contingency plan, so you don't get penalised. A bridging loan can be used as a short-term alternative to provide access to the funds before your mortgage is finalised.
It’s important to choose a mortgage deal you can afford, and make sure you understand any conditions and extra fees involved.
You can apply for a mortgage online or over the phone, depending on what works best for you.
How to get a mortgage for a new build property
Buying a new build property comes with some specific considerations for mortgage applicants:
Most mortgage offers are valid for six months. New build properties can take longer to complete, so you may need to apply for an extension or reapply closer to completion.
As some developers offer cashback or free upgrades, lenders need to be informed of any incentives upfront, as they can affect the lending terms.
Many new build flats are leasehold — ensure you check the lease length carefully, as lenders will typically require at least 70 to 85 years remaining above the mortgage term.
Some lenders apply stricter loan-to-value (LTV) limits on new build properties, particularly flats, so you may need a larger deposit than you would for an equivalent older property.
Other than these considerations, the mortgage process for a new build is much the same as for a more traditional property.